

Google Wallet
4.4

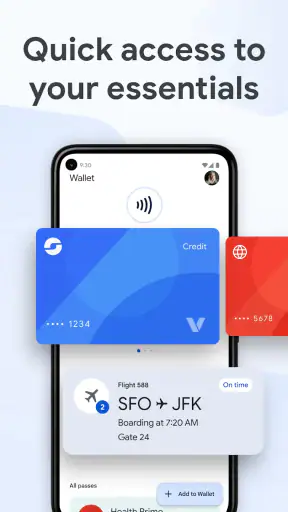
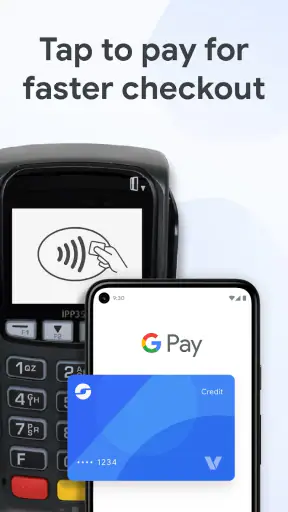
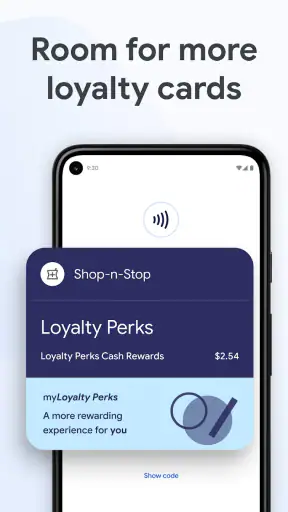
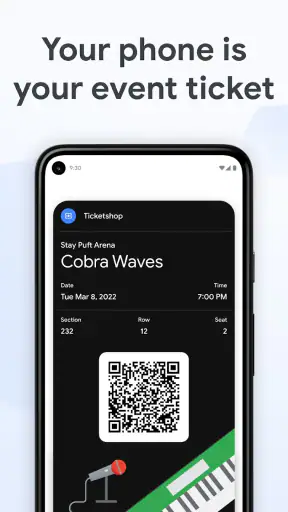
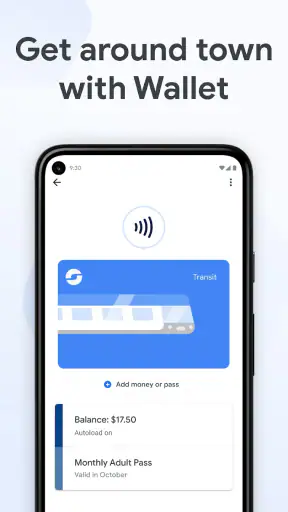
I find shared payments most useful when they remove a small bit of everyday friction rather than trying to replace every part of a household’s routine. Google Wallet can keep payment cards and other eligible items close at hand on a personal phone, which is handy when I’m heading out with groceries to pick up or need a ticket while carrying bags. The important boundary is that a digital wallet is still personal: putting a household card on one person’s phone doesn’t make it a shared wallet or automatically coordinate everyone’s spending.
When one person handles the errand
Picture a quick grocery run after work. I can use my phone at checkout instead of searching for a physical card, while a transit pass or ticket stored in the app may also be convenient on the same outing. That is a practical use for a household where one person often runs errands, but it does not replace agreeing in advance which card to use or how to track the purchase. The app makes access easier; the people involved still need to handle the household bookkeeping.
This distinction matters if several adults share expenses. Each person should understand whose card is being used and whether that card is appropriate for the purchase. I wouldn’t treat a card appearing in a wallet as permission to use it. For shared-device situations, keeping each person’s account and payment choices separate is the safer, clearer approach than passing around a phone that is already set up for someone else.
Personal setup, with sensible boundaries
Google Wallet is a finance app from Google LLC, and the basic idea is straightforward: add eligible cards, passes or tickets to the app on your own device. The app is free, has an Everyone age rating, and requires Android 9 or later on Android. Its broad availability is reflected in more than a billion installs, while its average rating is 4.4 from around 2.2 million ratings. Those figures show that it is widely used, but they don’t guarantee that every card issuer, merchant or item will work the same way for every person.
When I set up a phone, I’d first make sure the device is protected with a screen lock and that I’m signed in to the Google account I intend to use. Then I’d add only cards and passes that belong on that device. This is especially worth doing on a phone used by a teenager or occasionally shared with a partner: the wallet should not become a workaround for unclear account ownership. If another household member needs to pay, their own card and device are usually a cleaner arrangement.
One useful habit is to check the card shown in the app before tapping, particularly if you keep more than one payment method there. A quick glance can prevent using a personal card when you meant to use a household one. I’d also keep a physical payment option available when a purchase is important, because a phone can be out of battery, unavailable or simply not accepted at a particular checkout. A digital wallet is convenient, but relying on it as the only way to pay creates an avoidable single point of failure.
Coordination matters more than the tap
For couples or housemates, the app can make an individual’s routine smoother, but it does not settle shared-expense questions. Before adding a card used for household costs, agree on who may use it, what kinds of purchases belong on it, and how receipts or totals will be shared. That conversation is more useful than assuming the wallet itself will organize a budget. I’d keep the payment method tied to the person who is authorized to use it and use whatever separate budgeting routine the household already trusts.
There is a small but helpful distinction between storing a payment method and organizing the whole financial picture. Wallet access can shorten the checkout step; it is not a substitute for a joint account overview or a dedicated budgeting tool. If your main need is to split bills, monitor a household budget, or give several people coordinated access, a bank’s shared-account tools or a budgeting app may be a better fit. I’d use Wallet for the moment of payment and a separate system for the decisions around it.
It can also help to decide what should stay physical. A backup card is sensible for travel, unfamiliar shops or situations where a phone-based payment is inconvenient. For tickets and passes, I’d check that the item is available in the app before leaving rather than assuming every booking can be added. Keeping a confirmation or the original ticket route available until I know the digital version is ready avoids a last-minute scramble at a gate or entrance.
Setting Up and Getting Started
First things first, setting up Google Wallet is a breeze. You just need a Google account, and let’s be honest, who doesn’t have one these days? Once you're in, the app guides you through adding your credit or debit cards. If you’re like me and have a million different cards, don’t worry—Google Wallet has room for all of them.
One of the things I loved is the app's integration with other Google services. If you’re already using Google Pay, your payment methods sync up seamlessly. Plus, it supports loyalty cards and gift cards. It’s like having your entire wallet digitized, minus the bulk.
User Experience and Interface
The user interface is sleek and intuitive. It’s got that classic Google simplicity that makes everything easy to find. No more fumbling around trying to figure out where things are. I especially appreciate the smooth transitions and quick loading times. You can tell the developers put a lot of thought into making it user-friendly.
Another cool feature is the app’s ability to notify you of nearby deals and offers. Who doesn’t love saving a few bucks while shopping? It’s like having a savvy shopping buddy who always knows where the sales are.
Security Features
Now, let’s talk security—because no one wants their financial info floating around in cyberspace. Google Wallet uses multiple layers of security to keep your data safe. The app requires authentication before any transaction, and you can use a fingerprint or face recognition if your device supports it. I felt pretty secure using it, knowing that Google takes privacy seriously.
If your phone ever goes MIA, you can quickly lock your account remotely. It’s reassuring to know that even if your phone grows legs and walks away, your money doesn’t have to go with it.
Age, trust and household use
The Everyone rating makes the app broadly suitable for general audiences, but it doesn’t mean every child should independently manage payment cards. I’d treat age and responsibility as separate questions: a young person may be comfortable carrying a phone, while still needing an adult to decide whether any payment method belongs on it. The right setup depends on the cardholder, the device owner and the household’s expectations, not just the age label.
Trust also includes knowing what happens when a device is lost. The option to lock an account remotely is reassuring, but I would not wait until a phone disappears to think about recovery. I’d make sure the account owner knows how to secure the device and where to find the relevant account controls. If a phone is shared, one person should remain clearly responsible for its account and payment setup; casual handoffs make it harder to know whose credentials or card are in use.
Where it fits among payment options
Compared with carrying a physical wallet, the main advantage is quick access from a phone and less need to dig for a particular card. Compared with a bank’s own app, Wallet can feel more like a central place for everyday payment items, while a bank app is usually the better place to review account details and manage banking-specific tasks. I see them as complementary rather than competing: one can help at the checkout, while the other remains useful for checking balances or handling account matters.
There are good reasons to stick with a physical card or another payment option. If you prefer not to rely on a phone, need a method that works without unlocking or charging a device, or want several household members to access a common payment method, a physical card or properly shared financial account may suit you better. Acceptance and card eligibility can also vary, so I wouldn’t assume a digital wallet will cover every purchase. Keeping a backup avoids turning a convenient shortcut into a frustrating dependency.
For frequent shoppers, I’d add loyalty and gift cards only when they are items I actually use. A cluttered wallet is still cluttered, just on a screen. Keeping the useful items easy to spot makes checkout smoother, and checking the selected payment card before a tap is a simple safeguard when personal and household spending sit side by side. Those small habits matter more than trying to store every possible card.
Final Thoughts
Overall, Google Wallet is a fantastic app for anyone looking to streamline their payment methods and keep everything in one place. It’s user-friendly, secure, and integrates well with other Google services. Whether you’re a tech-savvy individual or just someone who appreciates convenience, this app is worth checking out.
So, if you haven’t yet embraced the world of digital wallets, now might be the perfect time. With Google Wallet, you’ll be ready to leave that old, bulky wallet behind and step into a future where everything is just a tap away.
My household verdict is that it works best as a personal convenience, not as a shared family payment hub. I’d recommend it to someone who already carries a compatible phone, wants cards or eligible passes close at hand, and is comfortable keeping their own account organized. I’d skip it as the primary solution for coordinating group spending, managing a shared budget or giving several people access to one payment method. Used with clear account boundaries and a backup way to pay, it can make ordinary errands easier without pretending to solve the household decisions that still need a conversation.
4.4
120.64K Reviews
Pros
- Seamless integration with Google services.
- Supports multiple payment methods.
- User-friendly interface.
- High security with advanced encryption.
- Easy transaction tracking.
Cons
- Limited compatibility with some banks.
- Availability may vary by region.
- Requires internet for most features.
- Not all stores accept it yet.
- Occasional app glitches reported.


